Posts

Showing posts with the label INTC

IB Net Payout Yields Model

Intel: Q2'26 Earnings Don't Impress

Image
Intel (INTC) jumped after reporting Q2 results that beat estimates, but the company didn't report impressive guidance for Q3. The semi. company only produced a Q2 EPS of $0.42 while guiding to only $0.38 for Q3. The results don't warrant a $100+ price. 

Intel: No Resolution To Foundry And AI Problems

Update - Oct. 23, 2025 Intel  beats weak guidance and hardly grows during an AI chip boom, market cheers anyway with weak guidance for Q4. The market just seems to get dumber and dumber. -Q3 Non-GAAP EPS of $0.23 beats by $0.22. -Revenue of $13.7B (+3.2% Y/Y) beats by $560M. Q4 Guidance  Revenue guidance of $13.4B vs. consensus of $13.37B EPS guidance of $0.08 consensus of $0.08 Original article posted on Oct. 7 Intel has surged despite no fundamental improvements in its foundry business or AI capabilities, making the rally appear irrational. The chip company has signed deals with Nvidia and the U.S. government for cash infusions provides liquidity but do not solve the lack of HPC foundry customers or AI solutions. IFS continues to report massive losses, and competitors like AMD and TSMC show no signs of meaningful collaboration with INTC on premium chips. The stock is extremely expensive at over 30x '27 EPS targets, investors are advised to use the rally to exit positions as ...

Intel Remains Broken

  Intel Corporation reported another mixed quarter in Q3, with relatively weak results while the market tries to celebrate earnings beating guidance. The chip company continues to focus on cutting costs and capex, while peers are moving full speed ahead with advanced AI GPUs and increasing foundry spending. The stock shouldn't be bought until Intel has turned around the business due to the stressed balance sheet and cash burn position. Looking for a portfolio of ideas like this one? Members of Out Fox The Street get exclusive access to our subscriber-only portfolios.  Learn More » Intel Corporation  ( NASDAQ: INTC )  stock jumped  after finalizing plans to slash thousands of jobs in a move that isn't a positive sign for the business. The once chip giant again  reported mixed results  in a sector with explosive growth. My  investment thesis  remains Bearish on the stock, especially on any major rally above $20. Read the full article on Seekin...

Mobileye: Damaged Goods

  Mobileye Global warns of inventory issues and expects 2024 guidance to fall far short due to excess supplies caused by double EyeQ ordering during Covid. The ADAS chip company guided to 2024 revenues of only $1.9 billion suggesting a bigger problem than the 6 to 7 million excess chip inventory at Tier 1 customers. MBLY stock still trades at an elevated 12x 2024 sales targets despite the 25% dip. Since going public via the spin-off from  Intel Corporation  ( INTC ) in late 2022,  Mobileye Global Inc.  ( NASDAQ: MBLY ) has constantly traded at a premium valuation. The ADAS chip company just announced a  massive warning due to inventory issues at the end of 2023. My  investment thesis  remains Bearish on the stock even after the nearly 25% loss in early trading today, January 4th. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please read the disclaimer page for more details. 

Mobileye Global: Still Priced For Perfection

Image
This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More »   Update - June 5, 2023 Intel dumping shares should cap the stock in MobilEye following the irrational double top at $46. -Mobileye Global (NASDAQ:MBLY) on Monday announced the commencement of a secondary stock offering of up to 35M of its class A shares by a unit of Intel (INTC). -The Intel (INTC) unit selling the shares in the offering is Intel Overseas Funding Corporation. Update May 25, 2023   The Wells Fargo analyst sounds really bullish, but the price target only offers 25% upside. The better bet is Luminar Tech. ( LAZR )  at these prices. -Mobileye (NASDAQ:MBLY) shares rose more than 4% in pre-market trading on Thursday as Wells Fargo started coverage on the autonomous driving semiconductor company with an overweight rating. -Analyst Aaron Rakers, who also put a per-share price target of $50 on Mobileye (MBLY), noted that the company is ...

Intel: Spending Itself Into A Hole

  Intel Corporation reported Q1 2023 results that were better than feared, but the company burned a ton of cash during the March quarter. The chip giant saw net debt soar during the quarter due the loss, large capex spending and the payment of the last large dividend. Intel Corporation stock is expensive at $30 with debt soaring, and with the best expectations for an EPS to top $2 not until 2025 at the earliest. Intel Corporation  ( NASDAQ: INTC ) got a quick pop on better than feared  Q1 2023 results , but the numbers by no means were good. The chip giant saw its only growing business unit see  a related stock collapse during the day after reporting their earnings. My  investment thesis  remains Bearish on Intel as the business starts losing money while investing aggressively into a very uncertain future, adding a large amount of risk to the story. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please review the disclaime...

Intel: Mobileye Trap

  The Mobileye IPO price has been cut by 40% to start. Intel continues to face delays and lower valuations for assets impacting the value of the stock. Investors should avoid the stock until the business has hit rock bottom and an actual turn has occurred. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More »   Day after day,  Intel  ( NASDAQ: NASDAQ: INTC ) continues to cut expectations leading to less shareholder value. The latest news has the long expected Mobileye IPO coming out at a much lower valuation leading to less funds raised by the  chip giant. My  investment thesis  remains Bearish on the stock. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please review the disclaimer page for more details. 

AMD: Already Baked In

Image
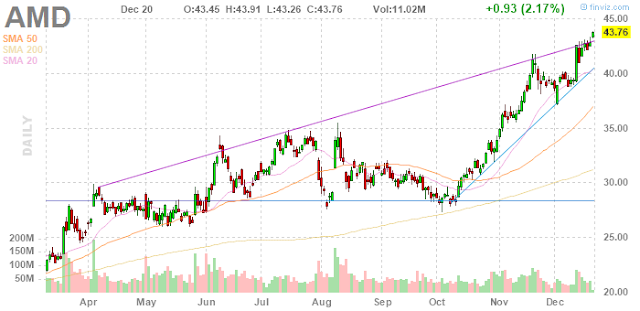
  AMD is now priced for serious weakness in the chip business while the data continues to support strong growth. The company remains supply constrained with Intel still forecasting chip challenges until 2024. The stock trades at only 15.5x '23 EPS targets, providing plenty of cushion for unexpected weakness. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More » Advanced Micro Devices  ( NASDAQ: AMD ) has fallen a massive amount this year that any major cut to financial targets is already baked into expectations. Amazingly, the chip company has faced a multi-year issue with supply  constraint problems, yet the stock market built a view of supply needing to already be cut. My  investment thesis  remains ultra Bullish on the chip company now trading below $90 due to the  Intel  ( INTC )  earnings disappointment . Top trending article on Seeking Alpha.  Read the full article ...

Intel: Still A Have Not

  Intel reported another quarter of weak results despite beating lowered guidance. The company forecasts a tough June quarter with another big EPS hit and revenues below expectations. The stock isn't exactly expensive around 13x forward EPS estimates, but Intel isn't appealing with the margin compression and negative trends. I do much more than just articles at Out Fox The Street: Members get access to model portfolios, regular updates, a chat room, and more.   Learn More » As with most recent quarters,  Intel  ( NASDAQ: INTC ) reported solid numbers compared to expectations, but the chip giant typically guides to ever increasingly weak numbers. The company is struggling with tough competition and taking on  risks by aggressive spending for the new fab strategy. My  investment thesis  remains very Bearish on the stock due to ongoing pressures on chip demand and market share losses. Read the full article on Seeking Alpha.  Disclosure: No posit...

AMD: Work From Home Boost

Image
The Work From Home economy is set to boost data center demand. AMD is poised to take market share from Intel in the growing data center space. The stock has long term EPS potential above $3 making the stock a bargain down at $40. The work from home economy has already boosted several companies in the virtual space which should lead to higher data center demand. While  Advanced Micro Devices  ( AMD ) has held up well in the downturn, investors have probably missed the boost in demand the company could see from the data center segment. My  investment thesis  continues to see the stock as a very compelling buy anywhere below $50. Read the full article on Seeking Alpha.  Update - March 27 Don't see the recent lows being broken. The risk is to the update as virus totals dip over the weekend in Europe and the US potentially hit peak new cases here soon. Disclosure: No position mentioned. Please review the disclaimer page for more details. ...

AMD: Right On Target

AMD updated their long-term financial targets at Financial Analyst Day 2020 to levels supportive of higher stock prices. The company guided to >20% revenue growth and 25% operating margins eliminating a long-held investor view of limited profits. The conservative outlook is for 2023 revenues of $15.0 billion and 2024 revenues at $18.0 billion suggesting revenues doubling from 2020 levels. My long-term model has an $18.75 billion revenue target (25% market share) and a $3.72 EPS. On March 5,  Advanced Micro Devices  ( AMD ) held their  Financial Analyst Day for 2020 . Despite the DJIA dipping nearly 1,000 points on the day and the COVID-19 fears spreading around the globe, the management team stayed focused on the long term. Read the full article on Seeking Alpha.  Disclosure: No positions mentioned. Please review the disclaimer page for more details. 

AMD: Good Enough

AMD slightly beat analyst estimates for Q4. The market is disappointed with Q1 guidance and the projected growth rates for exiting 2020. The stock trades below 25x a realistic 2020/2021 EPS target of $2. The initial dip following the  Advanced Micro Devices  ( AMD )  Q4 results  tells the main part of the story for the stock. Both bulls and bears will like the report, but the long-term story still favors the bulls. The  investment thesis  remains bullish as the chip company moves to capture market share in 2020 and beyond while the market desires higher growth rates exiting the year. Read the full article on Seeking Alpha.  Disclosure: No position. Please read the disclaimer page for more details. 

AMD: Not Priced For Perfection

Image
AMD isn't priced for perfection based on the Nvidia path. Investors tend to forget that AMD was priced for a financial disaster back in 2016. Nvidia has more normalized growth projections and still trades at 30x forward EPS estimates. My $15 billion revenue, $3 EPS plan would position the stock for substantial gains in the next few years inline with Nvidia from a few years ago. Due to the large rally in the stock of  Advanced Micro Devices  ( AMD ), investors consider the stock priced for perfection and pressured to meet lofty financial targets in 2020. The odd part is that  Nvidia  ( NVDA ) had a similar rally a few years ago and the stock traded at much higher peak valuation multiples than AMD is currently. The major separating fact is that AMD traded at distressed prices back in 2016 before these stocks rallied. My  investment thesis  remains very bullish on AMD due to the $15 billion sales plan. Read the full article on Seeking Alpha....

Ambarella: Back To Reality

Ambarella beat FQ3 results, but the management team suggested revenues of $10 million were pulled forward. After years of spending, the company still can't disclose any needle moving CV chip deals with automotive customers. The stock is likely to retest $40 with revenue estimates for FY20 and FY21 declining. Despite all of the promises of computer vision chips and the huge stock rally this year,  Ambarella  (NASDAQ: AMBA ) still hasn't generated anywhere near the results and forward expectations warranting the stock rally this year. Investors should expect the stock to come back down to earth based on my  previous research  due to falling expectations for the next couple of years consistent with the past of this chip company and risks of basically operating in China. Read the full article on Seeking Alpha.  Disclosure: No position. Please review the disclaimer page for more details. 

AMD: The $15 Billion Plan

Investors need to start considering a plan for AMD reaching $15 billion in annual sales. The company only needs to achieve a rather meager 25% market share in desktop, notebooks and server. The initial EPS target is $3 based on $15 billion in sales. The biggest negative against  Advanced Micro Devices  ( AMD ) is the general lack of current profits in relation to the stock price around $40. My  previous work  has focused investors on the drastically improving profit picture when the chip company gets to $10 billion in annual revenues. This article will focus on the next step of reaching $15 billion in annual revenues based on the company obtaining 25% market share in several key markets. Read the full article on Seeking Alpha.  Update - December 5, 2019 If these analysts would've only listened all year long, they wouldn't be raising the price target after the fact. - Baird reiterates a Neutral rating on AMD (NASDAQ: AMD ) and rais...

Intel: Better Lucky Than Good

Intel beat the Q3 revenue estimates due to luck from sales pulled forward and the immaterial nature of a competitor's ramp so far. Analysts are only forecasting the chip giant grows revenues in the 1% range while market share losses to AMD and Qualcomm will make this minimal target difficult. The stock trades at 12.3x forward EPS estimates while investors should expect estimate cuts. Intel  ( INTC ) has failed repeatedly over the last couple of years, yet the chip giant managed to  crush analyst estimates  in Q3. The company continues to prove it is better to be lucky than good as a prime competitor isn't able to ramp up supply of new chips fast enough to take meaningful market share in the near term. My  investment thesis  remains negative on the stock at the yearly highs despite the big quarterly beat. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please review the disclaimer page for more details.  ...

AMD: Shift Up To The Next Level

AMD might've slightly missed Q3 revenue targets, but the company confirmed a long-term bullish trend. Investors should focus on the Q4 revenue growth of 48% and annual run rate of $8.4 billion. The stock only trades at 20x a 2020 EPS target of $1.75. A realistic 2021 EPS target of $2.50 would help the stock achieve a $50 price target next year using a 20x P/E multiple. The stock didn't initially rally following  Q3 results , but  Advanced Micro Devices  ( AMD ) generated the results and guidance reinforcing our  investment thesis  that the stock hasn't reached full value. While the market was focused on a slight revenue miss, AMD is poised to see revenues trend much higher over the next couple of years driving the stock price even higher. Read the full article on Seeking Alpha.  More commentary - OutFoxThe$treet - November 5 Disclosure: No position mentioned. Please review the disclaimer page for more details. 

Intel Upside Capped By Yield

Image
Find it interesting that certain stocks appear to have capped upside based on the dividend yield.  Intel (INTC)  is such a stock when the yield hits the recent 2.4% levels. The stock might rally further to reach the recent highs, but the time to buy Intel is when the dividend yield tops 3.0%.  Read the full article on Seeking Alpha.  More  commentary  on WhoTrades . Disclosure: No position. See the  disclaimer  page for more details.  

AMD: Full Value Myth

AMD has taken a performance lead with the release of the Epyc 2 chips. New customers like Twitter and Google provide more confidence for 20% market share in the data center space. AMD doesn't trade at full value at $30. The stock has reasonable targets of $10 billion in revenues and a $1.75 EPS. For a few years now,  Advanced Micro Devices  ( AMD ) has attempted to reach the inflection point where their chips reached the price and performance that customers couldn't resist switching from the safety of the  Intel  ( INTC ) brand. The horizon was constantly shifting, causing consternation with the market participants that lacked faith in CEO Lisa Su and CTO Mark Papermaster. The release of Epyc 2 and other 7nm products finally has the company at the inflection point, allowing for disproof of the valuation myth and confirmation of our  bullish investment thesis  even with the stock up at $30. Read the full article on Seeking Alpha.  M...

Qualcomm: Take The Hint

Government departments are lining up against the FTC case on Qualcomm. The only benefit of an FTC win on appeal is foreign smartphone competitors. Qualcomm remains on target to generate $7 to $8 in annual earnings per share. The stock has a logical path to reach a $100 target with risks that the wireless giant doesn't eventually win on appeal. Qualcomm  (NASDAQ: QCOM ) finds itself in an odd position of having different parts of the government fighting over how to handle an antitrust ruling against the wireless chip giant. The key thrust of why the wireless giant is likely to win on appeals is the threat to national security and the global nature of the wireless handset business in 2019. The  bullish investment thesis  remains right on track despite analysts  heading to the sidelines  on risk concerns. Read the full article on Seeking Alpha.  More commentary - Out Fox The $treet - July 22, 2019 Disclosure: Long QCOM, AAPL. Please revi...