Posts

Showing posts with the label China

IB Net Payout Yields Model

XPeng: Morphing Into The Chinese Tesla

  XPeng delivered a standout Q3'25, with sales up over 100% and EV deliveries surging 149% year-over-year. XPEV's affordable Mona EV lineup drove record volumes, while the company pushes into robotaxi and humanoid robot markets, boosting its tech profile. Despite strong sales and improving margins, XPEV remains unprofitable, but forecasts a small Q4 profit and holds a solid cash position. Shares trade at a low valuation versus peers, offering an attractive risk/reward as XPEV evolves into a global tech leader beyond EVs. Only a year ago, the Chinese EV market appeared overly competitive, now, players like  Xpeng Inc.  ( XPEV ) are expanding far beyond just manufacturing vehicles. The company reported a solid Q3'25 with EV volumes far above prior year levels, but the  real excitement is in the robotaxi and humanoid robots opportunities. My  investment thesis  is Bullish, though one buying now has already missed a lot of the easy money over the last year or s...

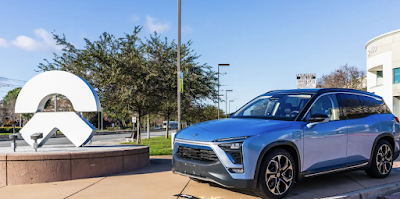
NIO: Looking To Take The Business To The Next Level

Image
  Update - Sept. 28, 2023 Not really sure what to make of NIO  possibly seeking even more investments. The converts were a disaster, but the stock has probably bottomed here on the potential Mercedes deal.  -NIO (NYSE:NIO) tracked higher in early trading on Thursday off a report that the Chinese electric vehicle maker has held exploratory talks with Mercedes-Benz Group AG (OTCPK:MBGAF) for a strategic tie-up. -Sources told Reuters that the proposed partnership would include the German automaker investing in NIO (NIO) in exchange for technology. NIO (NIO) CEO William Li is said to have discussed the potential collaboration with Mercedes-Benz (OTCPK:MBGAF) CEO Ola Kaellenius earlier in the year. However, there has been resistance within Mercedes-Benz (OTCPK:MBGAF) to pushing ahead with a deal and the talks reportedly did not reach a stage where details on the technology to be transferred and terms of a financial investment were discussed. Original article posted on Aug. 28 ...

NIO: Looking For A Breakout

Image
  NIO Inc. reported mixed March monthly vehicle deliveries of 10,378. The Chinese electric vehicle company still forecasts vehicle deliveries reaching a goal of 250K this year, which appears aggressive after only 31K in Q1. NIO stock is cheap at 1x EV/S multiples, with major multiple expansion possible on hitting breakout EV delivery targets for the year. The Chinese electric vehicle ("EV") space continues to struggle to rebound from covid restrictions and the lack of subsidies that caused a rush to purchase vehicles at the end of 2022.   NIO Inc.  ( NYSE: NIO ) has  fallen flat to start 2023, with sales growth not matching internal targets, though the EV company is making progress. My  investment thesis  remains ultra-Bullish on the breakout potential in the sector, though NIO continues to struggle to grow beyond prior sales peaks. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please read the disclaimer page for more det...

XPeng: Inflection Point Ahead

  XPeng Inc. reported mixed Q4 2022 results and guidance for 2023. The CEO was very bullish on the traffic around the P7i launch and the potential of the new G6 vehicle. XPEV stock is cheap at 1x '23 sales targets with plenty of catalysts for growth, while the cash balance will limit downside risk if the company fails to hit targets. The Chinese EV manufacturer reported generally  mixed Q4'22 results , but the market is more focused on what  XPeng Inc.  ( NYSE: XPEV ) projected for 2023. The Chinese market has only slowly reopened, in a major disappointment to investors expecting a  quick ramp-up in demand. My  investment thesis  remains ultra-Bullish on the stock trading at the recent lows, while the rebound opportunity remains massive. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please review the disclaimer page for more details. 

Freeport-McMoRan: Copper Will Rebound With China And EVs

Image
Freeport-McMoRan stock has dipped back to $40 with copper prices slipping back to $4/lb. Copper prices are set to rebound on a full China reopening and higher EV production levels. The stock will rally on higher copper prices while Freeport-McMoRan only trades at ~5x adjusted EBITDA targets. The China reopening has struggled to gain the expected steam due to an initial bout of high covid cases followed by the Chinese New Year.  Freeport-McMoRan  ( NYSE: FCX ) will ultimately benefit from the  surge in demand as the whole world throws resources into building EVs with high copper requirements. My  investment thesis  remains ultra Bullish on the copper miner, as lower copper prices have weakened the stock price since the start of 2023. Read the full article on Seeking Alpha.  Disclosure: Long FCX. Please review the disclaimer page for more details. 

XPeng: China Struggles Won't Last

XPeng Inc. got 2023 off to a slow start with weak January deliveries. With the Tesla, Inc. price cut, covid and the Chinese New Year, most Chinese consumers stayed on the sidelines looking for price cuts. The Chinese EV manufacturer predicts a big year ahead due to the new G9 SUV. XPeng stock is cheap, trading at only 1x '23 sales targets. The Chinese electric vehicle ("EV") market got off to a slow start in January, with  XPeng Inc.  ( NYSE: XPEV ) reporting a major sequential decline in monthly deliveries. The Chinese New Year and  Tesla, Inc.  ( TSLA ) price cuts impacted customer demand in the quarter. My  investment thesis  remains Bullish on a rebound in the Chinese EV sector, as much as on an XPeng gain with the stock still trading close to the lows. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please review the disclaimer page for more details. 

Freeport-McMoRan: China Will Roar Back

  Freeport-McMoRan now trades below a market cap of $45 billion despite delivering $12 billion in adjusted EBITDA over the last year. The copper miner is set to ride the wave of higher copper demand from China. The stock is cheap at current copper prices and only trades at 3x EBITDA targets for $5/lb copper. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More »   Like most commodities, copper has been crushed over the last few months, sending  Freeport-McMoRan  ( NYSE: FCX ) down for the year. The global economic weakness centered on China sent copper prices down to 20-month lows, but the communist country is back in  growth mode. My  investment thesis  is ultra bullish on the stock after the dip due to the ultimate strong demand for copper. Read the full article on Seeking Alpha.  Disclosure: Long FCX. Please review the disclaimer page for more details. 

Baidu: Delisting Fears Overplayed

Image
  Baidu faces a delisting risk due to the HFCA Act where U.S. regulators want access to Chinese audits. The company has 2 more years to meet audit requirements. The stock is exceptionally cheap at only 9x forward EBITDA estimates due to a massive cash balance. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More » Over the last month, the Chinese stocks have traded in a wild fashion due to fears the shares will be delisted from U.S. stock exchanges. The risks to  Baidu  ( NASDAQ: BIDU ) appear far over stated. My  investment thesis  remains very Bullish on the Chinese tech stock leading in autonomous vehicle technology, but Baidu definitely faces a volatile few years. Read the full article on Seeking Alpha.  Disclosure: Long BIDU. Please see the disclosure page for more details.  Update - Apr. 29 Big AV news for Baidu. The stock just isn't valued for this division.  Baidu ( NAS...

Freeport-McMoRan: Minting Cash

Image
  Freeport-McMoRan continues to benefit from high copper prices despite the recent dip from levels near $5/lb. At $4.50/lb, the copper miner produces FCFs in the $8 billion range and EBITDA reaching $15 billion. The stock is too cheap with a market cap of just $54 billion with the bullish long-term demand trend due to EVs. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.    Learn More » Freeport-McMoRan  ( FCX ) fell to nearly $30 on fears of slowing Chinese demand for copper, yet copper prices remain sky high. At current prices, the copper miner is poised to generate billions of dollars in annual free cash flows. My  investment thesis  is Bullish on the stock in the mid-$30s, though investors should take some profits due to the historically volatile prices for the red metal. Read the full article at Seeking Alpha.  Disclosure: Long FCX. Please review the disclaimer page for more details.  ...

Apple: Future Boost

Apple closes all retail stores outside Greater China and should take a large hit to FQ2 and FQ3 sales. The company had most China stores closed for about one month. The market will increasingly look towards FY21 sales that should see a boost from delayed spending. My estimate is for a FY21 EPS boost to $17, making the $250 stock cheap at 14.7x this target. Apple  (NASDAQ: AAPL ) has seen several analysts  cut price targets  on the stock due to cuts to FY20 numbers. Regardless, the stock remains a strong investment option based on normalized numbers not impacted by the coronavirus impact on the global economy. My  investment thesis  recommends investing in stocks based on FY21 numbers that might even get a boost from sales pushed into the next fiscal year. Read the full article on Seeking Alpha.  Disclosure: Long AAPL. Please review the disclaimer page for more details. 

Apple: Not Priced For COVID-19 Impact

Apple warned on FQ2 revenues missing estimates due to coronavirus impact. Analysts remain very bullish on the company's prospects long term. The stock only trades $8 away from all-time highs. The stock isn't a buy until more realistic expectations emerge for the COVID-19 revenues impact. In no real surprise,  Apple  ( AAPL )  warned on revenue estimates  for the current quarter only about three weeks since the company provided  robust expectations  for FQ2 despite some fears on the coronavirus. My  previous research  had warned the stock wasn't appealing in the $320 range due to low yields and the virus issue in China and this warning reinforces this thesis. Read the full article on Seeking Alpha.  Disclosure: Long AAPL. Please review the disclaimer page for more details. 

Apple: China Remains The Biggest Risk

The company has a Chinese business worth in the $45 billion range in FY19 partially at risk due to these trade tensions. The 2018 holiday results were crushed by abnormal results in China, while numerous other countries hit all-time record revenues. Any China hit would place Apple EPS estimates at risk due to a cut to FY20 revenue growth. The stock doesn't offer the ideal value at all-time highs with these risks. As  Apple  (NASDAQ: AAPL ) trades around all-time highs, the tech giant appears to have another China problem similar to last year. The U.S. government remains in a major trade war with the Chinese despite promoting major progress at negotiations last week. Several companies ran afoul of the Chinese government officials recently leaving a company like Apple vulnerable to losing one of the largest markets for the tech giant. My  long-term investment thesis  remains bullish, but buying the stock here while facing a China problem is a different ...

Baidu: No Google Threat

Google CEO confirmed the company wasn't planning on entering the Chinese search market. Oddly, Baidu ended down on the day despite this bullish news. The stock trades at only 13.5x '20 EPS estimates despite double the growth rate. Baidu   ( BIDU ) remains one of the more perplexing stocks in the market. Despite a blooming Chinese internet sector, the market always has an excuse for avoiding the stock. My long-term   investment thesis   hasn't changed, and the stock only becomes a better bargain on every dip. Read the full article on Seeking Alpha. 

Baidu: Another Gift

Baidu trades down $25 due to the departure of the COO from daily activities. The company has a long history of growth without the involvement of Qi Lu. The stock continues to trade favorably to domestic peers despite massive margins. Despite being a dominant player in the fast-growing internet space in China,  Baidu  ( BIDU ) consistently trades at a discount to American peers. The departure of a key executive and an analyst downgrade provide another gift to own this stock on a $25 dip and at levels from back in 2014. Read the full article at Seeking Alpha.  Disclosure: Long BIDU. Please review the disclaimer page for more details. 

Baidu: Hidden Value

Baidu remains a hidden tech giant in a market of $500 billion global giants. The Chinese search leader is returning to 30% revenue growth. The company has several hidden assets that the market is currently not ascribing any value. After a few years in self-imposed purgatory due to surging costs on new initiatives,  Baidu  (NASDAQ: BIDU ) is finally back to generating the massive profits from substantial revenue growth of the past. The combination of dumping the high-cost services businesses and a return to a healthy search market has the internet search giant of China back onto a path to higher stock prices. Read the full article on Seeking Alpha.  Disclosure: Long BIDU. Read the disclaimer page for more details. 

Baidu Will Thrive After Difficult Period

Baidu reports mixed results for Q2 while the market focuses on the length of the regulatory impacts. The stock continues to trade favorably to domestic Internet companies not facing short-term regulatory impacts. A couple of catalysts will provide ultimate upside for the stock once this difficult period passes. Tighter regulation in China continues to impact  Baidu  (NASDAQ: BIDU ) at the same time that  Facebook  (NASDAQ: FB ) and  Alphabet  (NASDAQ: GOOG )(NASDAQ: GOOGL ) are still experiencing explosive growth. The global economy continues shifting aggressively to digital and especially mobile advertising that should ultimately benefit Baidu. Read the full article at Seeking Alpha.  Disclosure: Long BIDU. Please review the disclaimer page for more details. 

Qihoo 360: Extreme Value Or Value Trap?

Summary Qihoo 360 easily surpassed analyst estimates for Q414. The Chinese Internet stock continues to trade at a compelling valuation forecast by one analyst at roughly 9x 2016 EPS estimates. The quarterly report did nothing to alleviate concerns that leave the stock in the value trap position. After the close on Monday, Chinese technology company Qihoo 360 Technology (NYSE: QIHU ) reported Q4 results that generally smashed analyst estimates. While the top line growth rate was phenomenal, the lingering issues that sent the stock plunging from over $120 to below $50 in the last year probably weren't resolved. Read the full article at Seeking Alpha. Disclosure: No position mentioned. Please review the disclaimer page for more details. 

Lessons Learned From The Yahoo Saga

Summary Alibaba surging to more than $93 on the first trading day provides substantial gains for Yahoo. Solid earnings should've kept investors owning Yahoo during the lean years for the stock. The inability to turn operations around probably caps the stock gains from here with the Alibaba gains captured. With the recent Alibaba (NYSE: BABA ) IPO providing riches for Yahoo (NASDAQ: YHOO ) , it's worth taking the time to discuss the lessons learned from the stock over the last decade. Though the stock has surged since the end of 2012, most long-term shareholders haven't seen any real gains with the stock, only now flat with levels reached back in 2006. In reality, a lot of investors probably dumped the stock despite knowing the potential gains in the Alibaba investments. Read the full article at Seeking Alpha. Disclosure: No positions mentioned. Please review the disclaimer page for more details. 

Higher Expenses Or Not, Baidu Is Cheap

Summary Baidu easily exceeded Q214 earnings estimates. The stock trades at a favorable valuation with multiple expansion. Chinese search stocks in general remain cheap. When last covering Baidu (NASDAQ: BIDU ) , the stock was under pressure due to fears over SEC bans on auditors in China. At the time in January of 2013, the stock slipped below $160 before an eventual bottom near $140 that April. Investors were encouraged to focus on mobile search growth and ignore the over flamed SEC concerns. Fast-forward to today and the stock is surging beyond $225 based on fast mobile growth. The crazy part is that investors might not be too late to invest in this story. Read the full article at Seeking Alpha. Disclosure: Long BIDU. Please review the disclaimer page for more details. 

Freeport-McMoRan Can't Overcome China Weakness

While signs existed last week that Freeport-McMoRan Copper & Gold ( NYSE: FCX     ) was close to a resolution in Indonesia, the stock is going to have a much harder time overcoming the plunging copper prices due to China. As with most commodities, China is the engine that drives demand and ultimately pricing of copper. In the last few years, the Asian power has grown to account for roughly 40% of copper demand worldwide. Freeport-McMoRan is a leading global mining company with interests in copper, gold, and oil. The miner has a mix of mines throughout North America, South America, the Democratic Republic of Congo, and Indonesia. The mix of commodities and geographic locations helps it overcome political issues in any particular country, but the one thing the company won't overcome is plunging copper prices due to weak demand in China. Read the full article here . Disclosure: No positions mentioned. Please review the disclaimer page for more details....