
Palo Alto Networks: Mismatched AI Cybersecurity Excitement
Update - Sept. 2, 2026
Palo Alto Networks with the solid beat as expected. The stock just has nowhere to go at this valuation, leading to the 9% dip following earnings. The cybersecurity company forecast a FY27 EPS of only $4.175 for only around 9% growth while the stock still trades at 78.5x EPS targets. The numbers just don't support the big rally.
-FQ4 Non-GAAP EPS of $1.02 beats by $0.04.
-Revenue of $3.41B (+34.3% Y/Y) beats by $60M.
These FY27 guidance numbers appear very low.
-Next-Generation Security ARR of $11.075 billion to $11.175 billion, representing year-over-year growth of 22% to 23%.
-Remaining performance obligations of $25.2 billion to $25.4 billion, representing year-over-year growth of 19% to 20%.
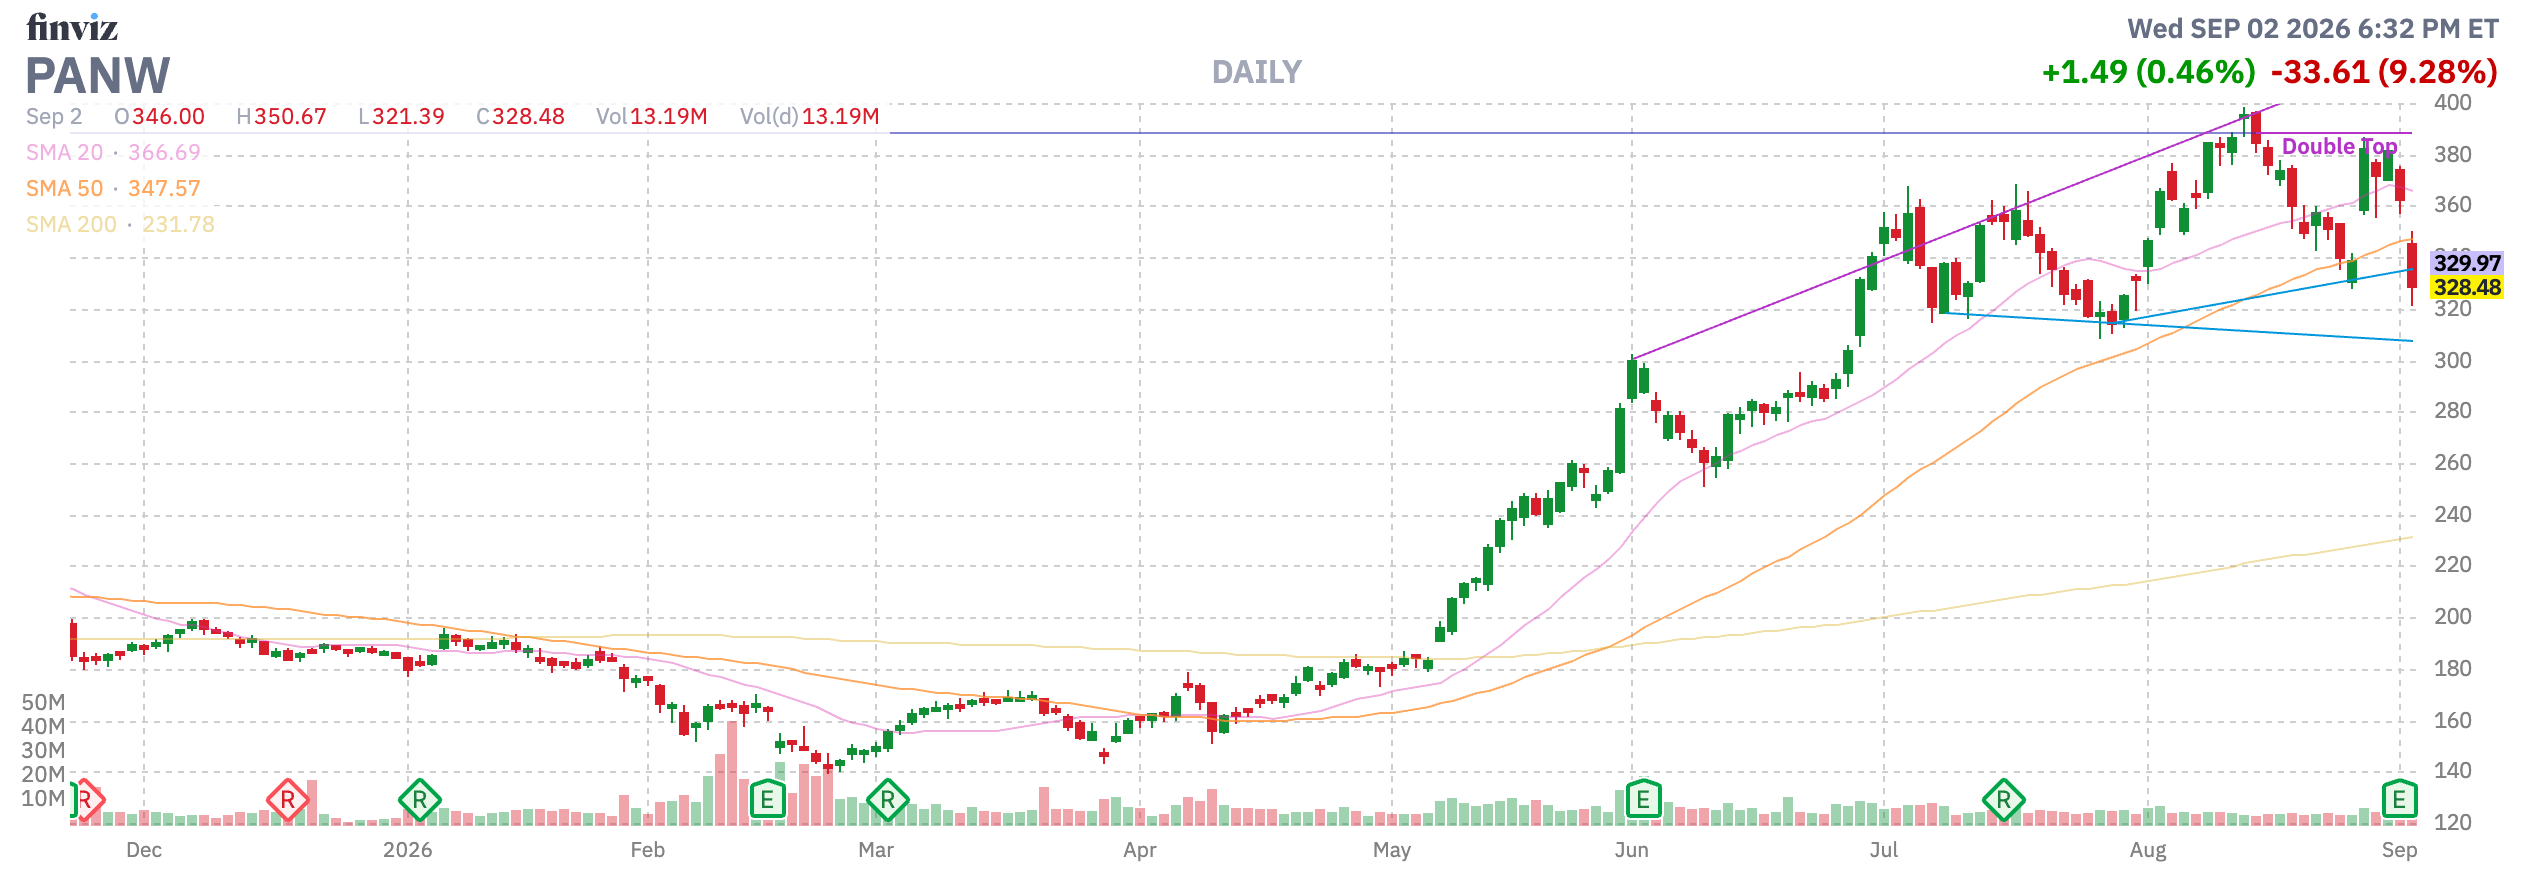
Original article posted on Aug. 29
- Palo Alto Networks trades near all-time highs, with the stock valuation far outpacing business fundamentals and organic growth trends.
- PANW's organic growth slowed to ~14% in the last quarter, while EPS growth is muted due to recent M&A, despite AI sector enthusiasm.
- Research shows that public mergers don't normally work out to boost shareholder return, and the cybersecurity company appears to be eager to head down that path again.
- The stock trades at over 22x forward sales and 100x FY26 EPS, with only mid-teen organic growth forecasted.
Comments