Posts

Showing posts with the label AMD

IB Net Payout Yields Model

AMD: Promising Upside By 2025

  Advanced Micro Devices, Inc.'s Q3 results and guidance initially disappointed the market, but the stock has rallied to multi-month highs. The launch of AI chips could drive the stock to all-time highs, with projected AI revenue exceeding $2 billion in 2024 alone. The stock trades at a base case of only 20x '25 EPS targets, but AI GPU chip sales could provide a substantial boost to conservative targets. After the market initially didn’t like the  Q3 results  and  guidance  from  Advanced Micro Devices, Inc.  ( NASDAQ: AMD ), the stock has suddenly rallied to multi-month highs. The launch of AI chips could send the stock  to all-time highs similar to peer stocks. My  investment thesis  remains ultra bullish on AMD, with investors best to focus on future numbers, not short-term hiccups around product launches. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please review the disclaimer page for more detai...

AMD: Strong Read From Nvidia's AI GPU Surge

  Nvidia reported explosive AI GPU sales growth and signals supply will support higher growth going forward. Advanced Micro Devices' competing AI GPU chip, MI300, is set to hit the market in Q4 and has significant capacity secured. The company has significant upside with analyst estimates not factoring in massive upside potential from AI GPU sales. AMD stock is cheap at closer to only 20x '24 EPS targets. After the close,  Nvidia  ( NVDA ) reported much anticipated results for the  July quarter . The company reported explosive AI GPU sales growth and signaled supply will support higher growth going forward. The news has huge implications for  Advanced Micro Devices  ( NASDAQ: AMD ) with a competing AI GPU chip hitting the market in Q4 and the numbers from Nvidia reinforce the statements from AMD management. My  investment thesis  remains ultra Bullish on the stock now trading at the recent lows despite a lot of bullish indications for upcoming gro...

AMD: A Second Half Growth Story

Image
Update - May 23, 2023 The market has definitely bought into the AI growth story and the 2H sales ramp. AMD hit a new 52-week high at $111 and probably rallies further falling a pause.    Original article posted on May 2 Advanced Micro Devices, Inc. reported mixed Q1 2023 results, beating analyst estimates, but revenues and EPS dipped from prior year levels. The chip company is poised for a second-half rebound, with the Client business rebounding and market share gains in data center and AI. AMD stock remains cheap, trading below ~20x consensus '24 EPS targets and far below normalized EPS targets. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More »   Based on the weak chip market,  Advanced Micro Devices, Inc.  ( NASDAQ: AMD ) wasn't expected to provide impressive results with  Q1 2023 numbers . The semiconductor company has always been poised for the next leg forward in the  2H of...

AMD: TSMC Predicts The Chip Bottom

  AMD continues to face a PC chip inventory correction that could impact Q1 results on May 2 and lower Q2 guidance. Investors got good news from TSMC forecasting a bottom in the inventory correction. The stock is cheap based on a quick ramp to a $5 to $6 EPS based on server demand and future AI chips. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More »   As  Advanced Micro Devices  ( NASDAQ: AMD ) heads towards reporting Q1'23 results on May 2, shareholders already got some positive indications from  Taiwan Semiconductor Manufacturing Company   Limited  ( TSM ). The chip manufacturer for leading advanced fabless  chip companies like AMD sees the prolonged chip inventory issue ending this quarter. My  investment thesis  is ultra Bullish on the stock expecting another $100 rally once the current chip inventory issue passes. Read the full article on Seeking Alpha....

AMD: AI Chip Boom

Image
  NVIDIA ushered in an AI chip boom with an inflection point in the current quarter. AMD announced several new AI chips in the last few months with plans to accelerate development and new product releases during 2023. The stock only trades at ~13x normalized EPS targets despite the long-term growth potential accelerated by AI chip demand. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More »   NVIDIA  ( NVDA ) soared this last week as the CEO told a bullish story on AI chip demand altering the narrative of a weak chip business due to slumping demand.  Advanced Micro Devices  ( NASDAQ: AMD ) recently told  a bullish AI story, but the stock didn't see the same bullish outcome. My  investment thesis  remains very Bullish on the chip stock solidly below $80 despite the bullish sector commentary. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Pleas...

AMD Remains In The Driver's Seat Following Intel's Q3 Earnings

  AMD reports Q3 earnings after the close on November 1. Intel provided every indication the chip giant has to boost margins and cut costs reducing any fears of the company dumping chips on the market. AMD remains cheap for the long-term opportunity in Datacenter, but the stock will trade volatile in the short term. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More »   Advanced Micro Devices  ( NASDAQ: AMD ) rallied to end last week after  Intel  ( INTC ) reported better than feared results. The chip giant was feared to have caused the inventory problem leading to the  big preliminary cut  to Q3'22 estimates for AMD. My  investment thesis  is very Bullish on the company ultimately taking market share from Intel as the inventory correction in the PC market is resolved by next year. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please re...

AMD: Already Baked In

Image
  AMD is now priced for serious weakness in the chip business while the data continues to support strong growth. The company remains supply constrained with Intel still forecasting chip challenges until 2024. The stock trades at only 15.5x '23 EPS targets, providing plenty of cushion for unexpected weakness. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More » Advanced Micro Devices  ( NASDAQ: AMD ) has fallen a massive amount this year that any major cut to financial targets is already baked into expectations. Amazingly, the chip company has faced a multi-year issue with supply  constraint problems, yet the stock market built a view of supply needing to already be cut. My  investment thesis  remains ultra Bullish on the chip company now trading below $90 due to the  Intel  ( INTC )  earnings disappointment . Top trending article on Seeking Alpha.  Read the full article ...

AMD: Not The $4 Billion Reasons To Own

Image
  AMD announced a $4 billion share buyback cheered by the market, yet only amounting to 3% of the combined company once adding Xilinx. The combined company expects billions in additional revenue by 2023 in comparison to when the merger was announced just in October. The stock is cheap as 2022 EPS estimates start pushing toward $3. This idea was discussed in more depth with members of my private investing community, Out Fox The Street.  Learn More » Now that Advanced Micro Devices ( AMD ) has dispelled the Intel ( INTC ) risks in the near term, investors can return to focusing on the long-term growth story of the chip company. The recent dip into the low $70s provided an opportune time for new investors to invest in this story alongside the company. My  investment thesis  remains highly bullish on the stock. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please review the disclaimer page for more details.   Update - June 2 Just ...

AMD: Imminent Break Of $50

Image
Despite the market uncertainties, AMD (AMD) remains a strong stock. In late Thursday trading, the sock ran into major resistance at $50. The chart appears to show a stock ready for a major breakout. My advice as long recommended this period is the last chance to buy AMD below $50. Any dip here is a buying opportunity. More research on Seeking Alpha: AMD: Work From Home Boost AMD: Right On Target AMD: Last Chance Below $50 Update April 10 Intel (INTC) says demand picked up for chips. Source: No position. Long in Out Fox model. Please review the disclaimer page for more details. 

AMD: Work From Home Boost

Image
The Work From Home economy is set to boost data center demand. AMD is poised to take market share from Intel in the growing data center space. The stock has long term EPS potential above $3 making the stock a bargain down at $40. The work from home economy has already boosted several companies in the virtual space which should lead to higher data center demand. While  Advanced Micro Devices  ( AMD ) has held up well in the downturn, investors have probably missed the boost in demand the company could see from the data center segment. My  investment thesis  continues to see the stock as a very compelling buy anywhere below $50. Read the full article on Seeking Alpha.  Update - March 27 Don't see the recent lows being broken. The risk is to the update as virus totals dip over the weekend in Europe and the US potentially hit peak new cases here soon. Disclosure: No position mentioned. Please review the disclaimer page for more details. ...

AMD: Right On Target

AMD updated their long-term financial targets at Financial Analyst Day 2020 to levels supportive of higher stock prices. The company guided to >20% revenue growth and 25% operating margins eliminating a long-held investor view of limited profits. The conservative outlook is for 2023 revenues of $15.0 billion and 2024 revenues at $18.0 billion suggesting revenues doubling from 2020 levels. My long-term model has an $18.75 billion revenue target (25% market share) and a $3.72 EPS. On March 5,  Advanced Micro Devices  ( AMD ) held their  Financial Analyst Day for 2020 . Despite the DJIA dipping nearly 1,000 points on the day and the COVID-19 fears spreading around the globe, the management team stayed focused on the long term. Read the full article on Seeking Alpha.  Disclosure: No positions mentioned. Please review the disclaimer page for more details. 

AMD: Good Enough

AMD slightly beat analyst estimates for Q4. The market is disappointed with Q1 guidance and the projected growth rates for exiting 2020. The stock trades below 25x a realistic 2020/2021 EPS target of $2. The initial dip following the  Advanced Micro Devices  ( AMD )  Q4 results  tells the main part of the story for the stock. Both bulls and bears will like the report, but the long-term story still favors the bulls. The  investment thesis  remains bullish as the chip company moves to capture market share in 2020 and beyond while the market desires higher growth rates exiting the year. Read the full article on Seeking Alpha.  Disclosure: No position. Please read the disclaimer page for more details. 

AMD: Possible Three-Peat In 2020

AMD topped the S&P 500 with a nearly 150% gain in 2019 after leading the index in 2018. Investors shouldn't bet on a three-peat performance, but the stock has the possibility for another strong year. My 2020 EPS estimate remains $10 billion revenues, $1.50 EPS plus a longer term $3+ EPS target. One of my  favorite picks  in 2018 and 2019 ended on a strong note last year. The prospects of  Advanced Micro Devices  (NASDAQ: AMD ) repeating the strong gain a third year wouldn't appear high, especially topping the S&P 500 for a third consecutive year. After all,  Nvidia  (NASDAQ: NVDA ) followed huge gains in 2016 and 2017 with a down 2018. Investors shouldn't bet heavily on a three-peat with AMD, but the stock remains poised for a strong run in the '20s decade. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please review the disclaimer page for more details.  

Out Fox The $treet - December 31, 2019

Image
Stocks to watch on the last day of 2019: AMD (AMD) - Rosenblatt raises the price target for the chip stock to $65. Analyst Hans Mosesmann has a similar view on the stock as Stone Fox Capital. The stock remains extended as 2019 comes to close. Investors will want to look for a pullback to start 2020 after the massive year end rally. Cronos Group (CRON) - pot stocks are seeing a big rally to end 2019. Cronos Group is up 17%, but the move just appears a dead cat rally. Don't chase any of the Canadian cannabis stocks higher. Disclosure: No position. Please review the disclaimer page for more details. 

AMD: Not Priced For Perfection

Image
AMD isn't priced for perfection based on the Nvidia path. Investors tend to forget that AMD was priced for a financial disaster back in 2016. Nvidia has more normalized growth projections and still trades at 30x forward EPS estimates. My $15 billion revenue, $3 EPS plan would position the stock for substantial gains in the next few years inline with Nvidia from a few years ago. Due to the large rally in the stock of  Advanced Micro Devices  ( AMD ), investors consider the stock priced for perfection and pressured to meet lofty financial targets in 2020. The odd part is that  Nvidia  ( NVDA ) had a similar rally a few years ago and the stock traded at much higher peak valuation multiples than AMD is currently. The major separating fact is that AMD traded at distressed prices back in 2016 before these stocks rallied. My  investment thesis  remains very bullish on AMD due to the $15 billion sales plan. Read the full article on Seeking Alpha....

AMD: The $15 Billion Plan

Investors need to start considering a plan for AMD reaching $15 billion in annual sales. The company only needs to achieve a rather meager 25% market share in desktop, notebooks and server. The initial EPS target is $3 based on $15 billion in sales. The biggest negative against  Advanced Micro Devices  ( AMD ) is the general lack of current profits in relation to the stock price around $40. My  previous work  has focused investors on the drastically improving profit picture when the chip company gets to $10 billion in annual revenues. This article will focus on the next step of reaching $15 billion in annual revenues based on the company obtaining 25% market share in several key markets. Read the full article on Seeking Alpha.  Update - December 5, 2019 If these analysts would've only listened all year long, they wouldn't be raising the price target after the fact. - Baird reiterates a Neutral rating on AMD (NASDAQ: AMD ) and rais...

Out Fox The $treet - November 25, 2019

Image
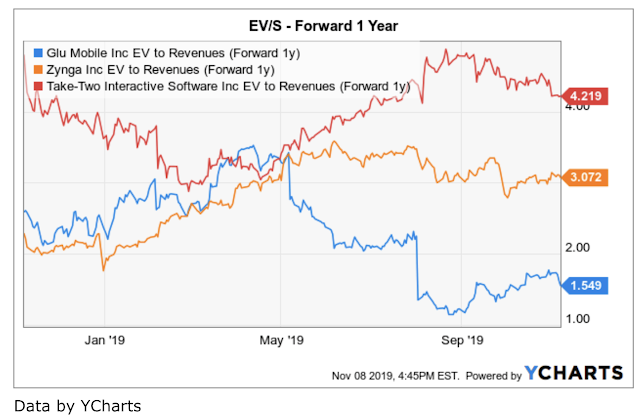
Stocks to watch on Monday for the shortened Thanksgiving week: Glu Mobile (GLUU) - the market cap is down to $750 million with the stock down to nearly $5. The valuation remains as compelling as the chart from earlier in November. Glu Mobile is an absolute bargain whether or not Disney Sorcerer's Arena is a hit in Q1 or not. Aurora Cannabis (ACB) - the conversion of substantially all of a C$230 million convertible debt was a positive move for the company. The stock will suffer in the short term as these new shareholders have no restrictions on dumping the stock. Aurora Cannabis will need more cash to fund operating losses. As the company resolves some more of their funding issues and 2020 catalysts kick into full force, the stock will become a buy when the stock reaches $2. AMD (AMD) - new Ryzen Threadripper chips are just another reason to own AMD on the path to $50 and possibly much higher. The chip company is only starting the process of taking market share from ...

Out Fox The $treet - November 18, 2019

Image
Stocks to watch on Monday: T-Mobile (TMUS) - CEO John Legere is stepping down May 1, 2020. The news is very negative for a wireless company that has thrived under his leadership. The stock needs to fall 10% to 20% before becoming an interesting investment without John as the CEO. Especially worrying is that the Sprint (S) deal isn't even done yet. The stock appears set for a new downtrend when $76 doesn't hold. AMD (AMD) - Cowen lifts the price target by $7 to $47. My research already lined out the path to $50 without meeting with CEO Lisa Su. The problem here is that investors needed to aggressively buy on the October dip to $28 and not this recent surge to $39. More research: AMD: Shift Up To The Next Level Aurora Cannabis (ACB) - the Canadian cannabis stock has broken below the downtrend. The valuation is starting to get appealing with several catalysts for the market to grow in 2020. The key is to let this trend play out and likely look for an entry point possi...

Out Fox The $treet - November 15, 2019

Image
Stocks to watch on Friday: Aurora Cannabis (ACB)  - the large Canadian cannabis company continued the pattern of horrible September quarterly numbers. The company made steps to curb supply, but Aurora Cannabis still produced 41K kg in the quarter and only sold 12K kg. The market valuation is still a rather high $3.6 billion with quarterly revenues of only $57 million. The FQ1 results were the first big signs of rationalization in the sector, but also only a small step before Aurora Cannabis becomes a buy with an Adjusted EBITDA loss of C$40 million.  AMD (AMD)  - RBC raised the price target to $50 from $44. AMD remains in a major breakout towards $50, but the recent rally appears stretched. The stock might retest $36 here.   Fitbit (FIT)  - worth watching here with the stock trading down to $6.80. Some skepticism exists on whether the government allows  Alphabet (GOOG)  to buy Fitbit. The merger arbitrage is only about $0.55 now, but some...

Intel: Better Lucky Than Good

Intel beat the Q3 revenue estimates due to luck from sales pulled forward and the immaterial nature of a competitor's ramp so far. Analysts are only forecasting the chip giant grows revenues in the 1% range while market share losses to AMD and Qualcomm will make this minimal target difficult. The stock trades at 12.3x forward EPS estimates while investors should expect estimate cuts. Intel  ( INTC ) has failed repeatedly over the last couple of years, yet the chip giant managed to  crush analyst estimates  in Q3. The company continues to prove it is better to be lucky than good as a prime competitor isn't able to ramp up supply of new chips fast enough to take meaningful market share in the near term. My  investment thesis  remains negative on the stock at the yearly highs despite the big quarterly beat. Read the full article on Seeking Alpha.  Disclosure: No position mentioned. Please review the disclaimer page for more details.  ...