Posts

IB Net Payout Yields Model

Staggering Chart of the Decade of Losses at AMR Corp

Image
Below is great picture from a TulsaWorld article of the continual losses by American Airlines parent AMR Corp (AMR). In good years, AMR makes a decent profit. In bad years, AMR has crushing losses. Even worse is the fact the losing years outweighed the good years 8 to 3 accumulating in a net loss of roughly $10.5B. How has this company even survived? AMR recently made the historic aircraft order that some say was needed to survive. Sure it makes them more competitive, more appealing to customers, but how are they going to pay for the planes. Per my recent article , still see the airplane lessors  as the winners. Companies like AerCap Leasing (AER) will continue to benefit from major airlines that need new fuel efficient planes to compete, but can't afford to buy them.  This quote sums it up the best: "American can't really afford to do this, but they cannot afford not to do it," said Robert Herbst, industry analyst and founder of AirlineFinancials.com. "...

Disconnect Between Crude OIl & Gas Prices

Image
Retail gas prices remain very elevated as seen in the chart below from Chartfacts.com. Beginning around May when oil prices plunged, gas prices remained relatively steady. Only falling as oil continued dropping below $100. According to the chart, the average price of gas needs to fall $0.30 to equal the fall in oil prices. Supposedly a lot of the price difference is caused by the price of Brent crude being higher than the Nymex/WTI quoted version. The main culprit for the price difference is the congestion and glut in Cushing, OK. Evidently they've built more pipelines coming into Cushing than ones leaving. Nice! Basically America has increased oil production to such an extent that now consumers aren't even getting the advantages. Brilliant! So while Congress is busy debating the debt ceiling our energy policy continues to be less than desirable. Wonder how many Congress members read the announcement from Chesapeake Energy (CHK) on the Utica Shale discovery ? Policy discu...

Manitowoc Decimated After Earnings, Fills Gap

Image
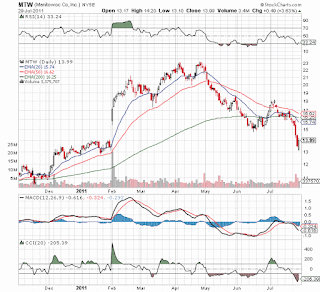
Incredible negative action in Manitowoc (MTW) after earnings Tuesday night. The stock dropped from $16 on Monday to $13 around the opening on Friday. Of course, the market was very weak contributing to the drop, but it was amazing to see the level of selloff in this particular stock. MTW is a leading crane maker and competes with Terex (TEX) among other companies. What really amazes this investor is that TEX had recently reported strong sales and weak profits leading any skilled investor to know the playbook for MTW. In fact, MTW actually reported stronger cranes numbers than TEX making any serious investor dizzy seeing MTW plummet. Luckily Stone Fox Capital unloaded MTW in the $15.8x range last Friday noting the stock was technically falling apart. Not to mention it had a gap around $14 in the charts suggesting the stock might fall substantially. Unfortunately we weren't able to return to the position in the low $13s this morning. The stock will be on are radar next week thoug...

Fastest Earnings Growth: Accuride and Meritor

his is the third in a series on stocks with the fastest estimated earnings growth in 2012. The first two articles focused on  Take Two Interactive ( TTWO ) with estimates expected to grow over 400% and  Patriot Coal ( PCX ) with numbers expected to nearly triple. The third fastest growing company is Manitowoc ( MTW ) with earnings expected to grow over 220%. Since we recently wrote a  report on the crane sector  which included MTW and the number six fastest grower in Terex ( TEX ), this article will focus on the next two stocks on the  SteetAuthority  list . Accuride ( ACW ) and Meritor ( MTOR ) supply parts to the automobile industry. Both companies were forecasted to grow earnings by roughly 220% next year. Likely both companies are relatively unknown by the investment community, which is one of the major benefits of such analysis. Focusing on just the names that hit the media outlets can cause investors to ignore under the radar investment ideas. Read ...

Nice Results from Radware

After disappointing results from Riverbed Tech (RVBD) and F5 Networks (FFIV) in the cloud networking space, Radware (RDWR) came through with excellent numbers today. RDWR continues to be the under the radar play in this general sector partly because they maintain a reasonable growth rate of only 17% half that of the numbers reported by RVBD. RDWR reported earnings of $.32 that beat estimates by $.03. Revenue of $41.1M was also slightly ahead of estimates. More importantly, RDWR guided to $.33 - .35 versus the $.33 analyst estimate. Not to mention that the CEO provided the tidbit that the numbers were conservative. RDWR is taking advantage of the move to cloud computing and data center consolidation. They also are in the process of opening up some key OEM relationships that could lead to a further revenue surge. It remains a core holding in our Opportunistic models and based on these results they should stay that way for a long time. Our goal is to hold these stocks for years if t...

Puda Coal Receives Draft Merger Agreement from Chairman

The buyout of Puda Coal (PUDA) is becoming increasingly likely considering the Chairman of the Board submitted a draft merger agreement last week. Though slightly delayed from the expectations of a submission in June, it still backs up his intent to follow through with the proposal from April 29. The delay also isn't too surprising considering the ongoing investigation into his supposed illegal transfers of company assets. Naturally the details of the merger agreement are more important than just the submission. No guarantee exists that the terms are agreeable. Or whether the price matches the desires of at least some shareholders that think $12 is too low. Will the special committee and BOD be able to negotiate a higher price? It would seem a difficult pill for most shareholders to swallow if Ming Zhao was able to cause the fear and parlay that into a cheap buyout. Also notable, PUDA submitted plans to regain compliance with NYSE listing standards. Though this might not be th...

Schlumberger Earnings Portend Good News for Weatherford

Image
Schlumberger (SLB) reported growing international demand (finally!) this morning on the Q2 earnings report suggesting that Weatherford (WFT) will have good results as well. Naturally WFT isn't as good of an operator as SLB so it could still surprise the market. WFT gets over 60% of its revenue from outside the US so it only benefits to a minor degree on the huge increase in US land drilling. It has also had problems this year with accounting issues and hence the stock price was recently approaching 52 week lows while big brother SLB and Haliburton (HAL) hit highs. Interesting to see bullish comments about deepwater markets, Egypt, and Bahrain. Also, noteworthy is that oil producers are ramping up production in other areas to make up for the lost production in Libya. All the news points to significant gains by WFT if they can turn it around. Looking at the charts below, it has a lot of catching up to get back to where SLB has gone this year. SLB Q2 PR : Income from cont...