
Bloom Energy: Not Pricing In Capacity Upside
Update - Nov. 5, 2026
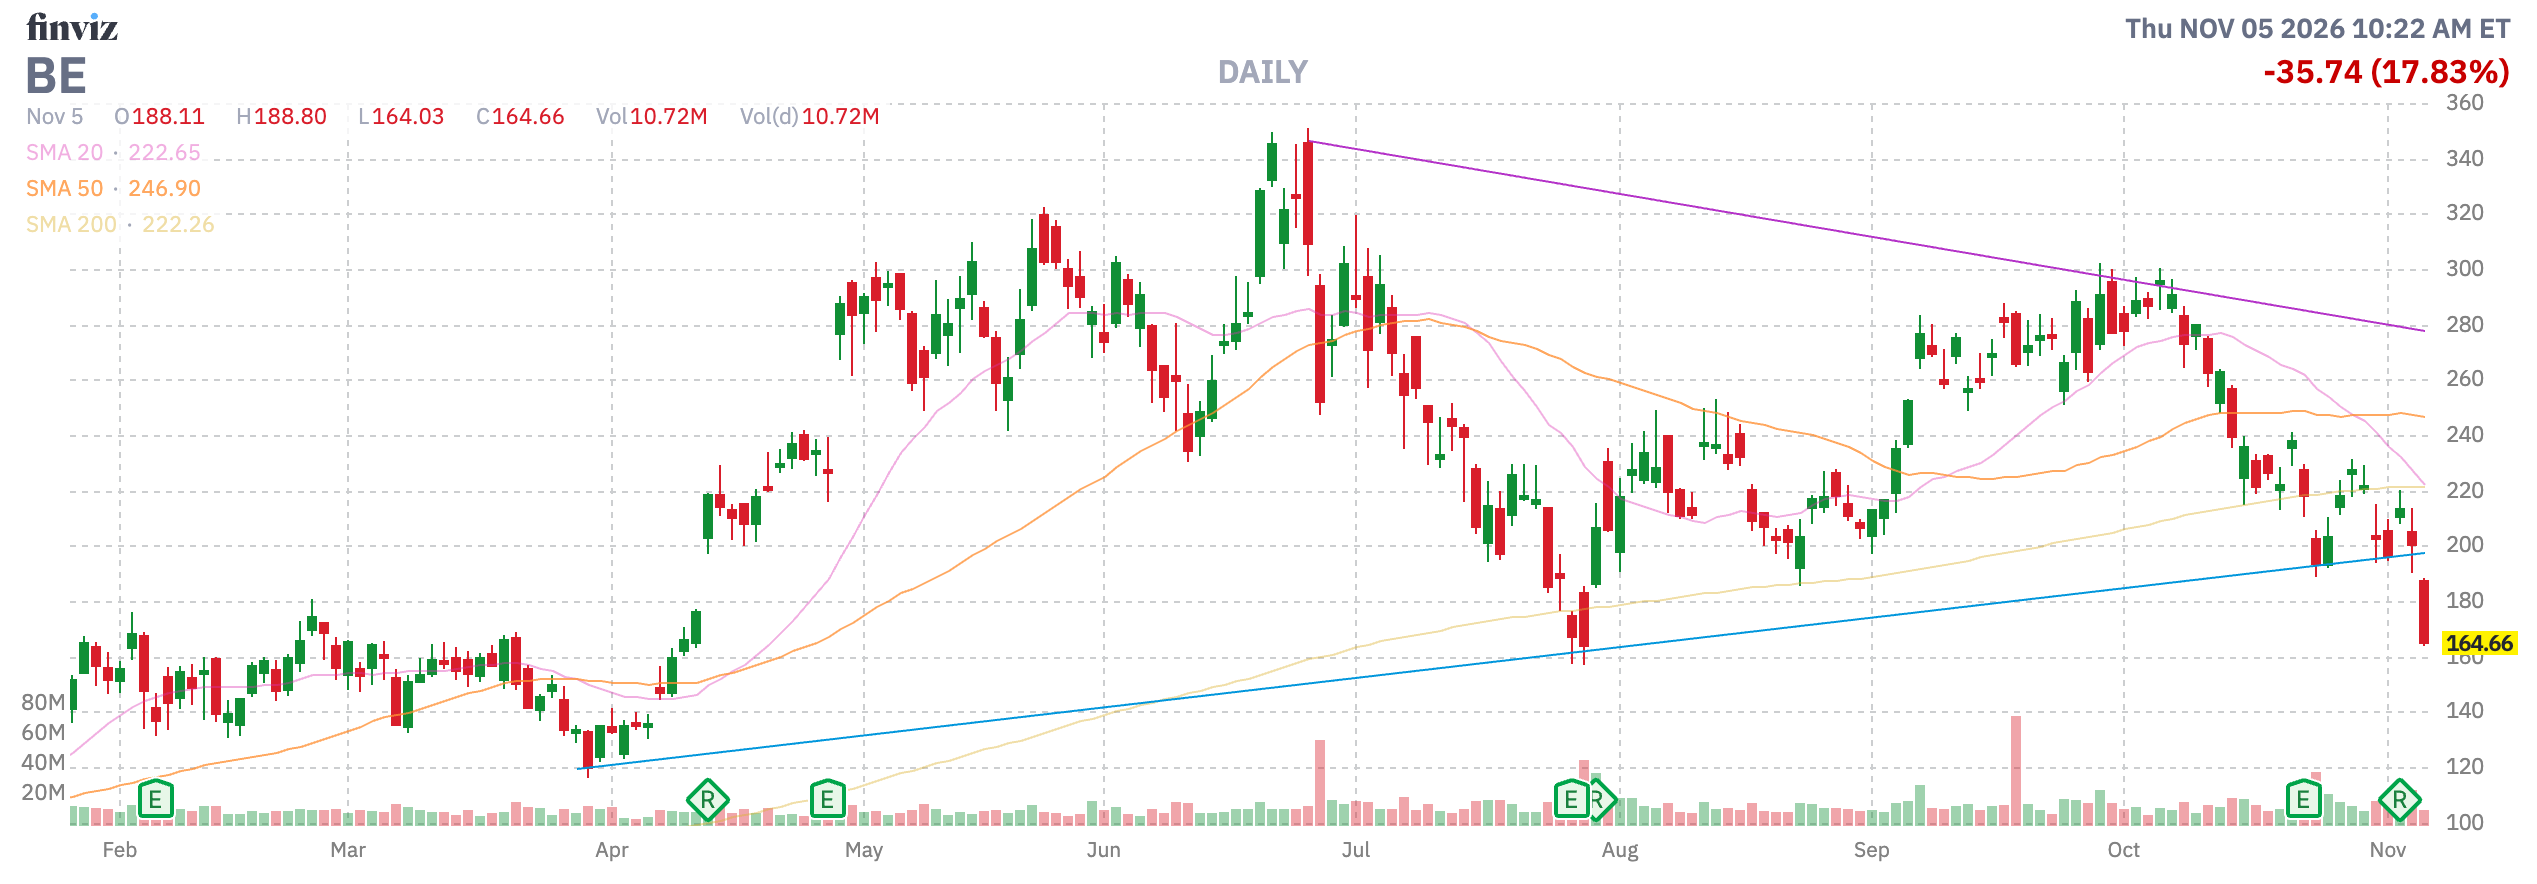
Wild to see BE down 15% today after the good news from CA and the analyst upgrade. If anything, Bloom Energy will be in more demand going forward. Note, the potential 1 GW deal in CA alone is nearly equal to 2026 sales.
-Bloom Energy popped 8.9% in Tuesday's trading after Barclays upgraded the stock and the company unveiled a potential large-scale power partnership with California Resources Corp. to evaluate the potential development of at least 1 GW of fuel cell power generation paired with carbon capture and storage in the state.
-Barclays upgraded Bloom (BE) to Overweight from Equal Weight with a $289 price target, saying demand appears to be inflecting more sharply than previously expected, as customer deposits increased from $78M in year-end 2025 to $661M in Q3 2026, including a ~$300M sequential increase in Q3 alone.
Original article posted on Oct. 24
- Bloom Energy delivered blockbuster Q3 '26 results, guiding up for Q4 and projecting robust long-term growth in data center power solutions.
- BE is rapidly expanding capacity, targeting over 5 GW and potentially $20 billion in annual revenue, with major customers like Oracle and Nebius driving demand.
- Despite recent negative cash flow from inventory and equipment build, the fuel-cell power company maintains a strong $2.5 billion cash balance and positive YTD free cash flow.
- The stock valuation isn't high based on '28 EPS targets, while current forecasts underestimate earnings power as capacity and operating leverage scale.
Comments